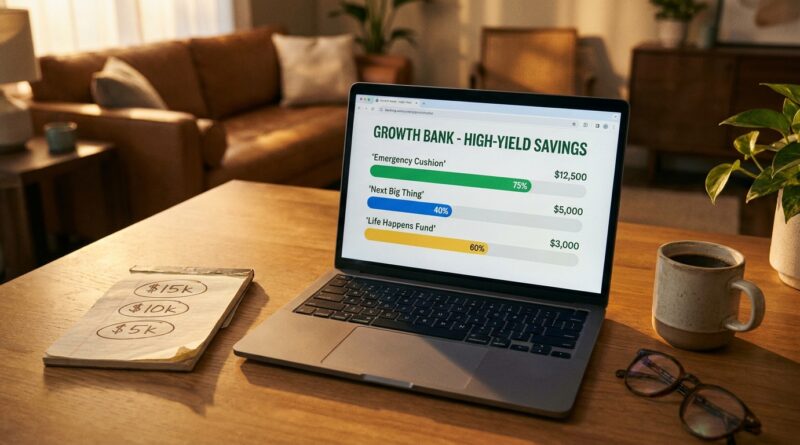
The ‘Split-Target HYSA Buckets’ Habit: One Login, Three Goals, Zero Guilt Spending
Your savings account is supposed to make you feel safe. Instead, for a lot of people, it feels like one big pile of stress. You look at the balance and think, “Can I use this for the car repair?” Then five seconds later you panic because maybe that money was really for emergencies. Or a trip. Or moving costs. Or the holidays. That is the problem with the usual advice to just “put money in a high-yield savings account.” It sounds simple, but real life is not one neat category.
A better fix is a high yield savings bucket strategy. One login. Three labeled buckets. A simple transfer routine that runs every payday. This setup helps you stop treating all savings like glass you are afraid to touch. Instead, each dollar gets a job. You protect your emergency fund, save for something fun or important, and cover those annoying surprise expenses without reaching for a credit card. It is practical, low effort, and you can set it up tonight.
⚡ In a Hurry? Key Takeaways
- Use one high-yield savings account with three buckets: emergency, near-term goal, and life happens.
- Automate transfers on payday so each bucket grows without you having to think about it.
- This setup helps you spend from the right category without guilt and lowers the odds of using credit cards for irregular expenses.
Why one big savings balance feels so stressful
When all your savings sits in one unlabeled account, every withdrawal feels risky.
You are not sure what is “safe” to spend. So you either avoid using the money even when you should, or you dip into it and feel bad later. Neither feels good.
This is why the high yield savings bucket strategy works so well. It keeps the benefits of a strong interest rate, but it adds clarity. And clarity is what turns “I should save more” into an actual habit.
The three-bucket setup that makes real life easier
You do not need five apps, ten accounts, or a color-coded spreadsheet. Start with three buckets inside one HYSA, if your bank allows it, or three clearly named savings categories if it does not.
1. Emergency Fund
This is your true safety net. Job loss. Major medical bill. Urgent car repair that threatens your ability to get to work. The boring but important stuff.
Rule of thumb: do not use this bucket for planned spending or “it would be nice” purchases.
2. Near-Term Goal
This bucket is for something you can picture. Travel. A move. A wedding expense. New furniture. A course you want to take.
This matters more than people realize. Saving is easier when at least one bucket is tied to something you are excited about.
3. Life Happens
This is the secret weapon. It covers irregular but normal expenses like car maintenance, pet bills, back-to-school costs, holiday spending, copays, gifts, or replacing a dead phone.
These expenses are not really emergencies. They are part of life. Giving them their own bucket helps you stop treating every surprise like a crisis.
How to split your money without overthinking it
You do not need the perfect formula. You need a formula you will actually keep using.
A simple starting split
Try this with each payday transfer:
- 50% to Emergency Fund
- 30% to Life Happens
- 20% to Near-Term Goal
If your emergency fund is already in decent shape, flip it:
- 30% to Emergency Fund
- 30% to Life Happens
- 40% to Near-Term Goal
The exact percentages matter less than consistency.
Another easy option
Use flat dollar amounts instead of percentages. For example:
- $75 per paycheck to Emergency Fund
- $50 to Life Happens
- $25 to Near-Term Goal
Small numbers count. Really. A system that runs every payday beats a big plan that only happens twice a year.
How to set up the routine in about 15 minutes
Step 1: Pick a HYSA that allows buckets or labeled goals
Many online banks now let you create savings categories inside one account. If yours does not, you can still do this by opening separate savings subaccounts at the same bank.
Step 2: Name the buckets like a real person
Skip vague labels like “Savings 2.” Use names that make sense at a glance:
- Emergency Only
- Italy Trip 2025
- Car, Vet, Holidays
If the label is clear, the choice gets easier when you need the money.
Step 3: Tie transfers to payday
This is the habit that makes the whole thing work. Schedule the transfer for the same day you get paid, or the morning after.
That way the money moves before it gets mixed into everyday spending.
Step 4: Give yourself one review date per month
Not every day. Not every time you are bored. Once a month is enough for most people.
Check whether the split still fits your life. If a move is coming up, maybe the near-term bucket gets more for a while. If your car is ancient, maybe Life Happens needs extra padding.
What “zero guilt spending” actually means
It does not mean spending without limits. It means spending from the right bucket without the usual panic spiral.
If your travel bucket has money in it, you can book the flight. If your Life Happens bucket covers new tires, you can pay for them without stealing from rent or running up a card. If your emergency bucket stays untouched, that is a win.
This is a healthier way to think about money. Not all spending is bad. Planned spending is exactly what savings is for.
Common mistakes to avoid
Making the emergency bucket do everything
If every non-monthly expense comes from “emergency savings,” the account stops feeling reliable. Then you feel behind even when you are trying hard.
Creating too many buckets
Three is enough to start. More buckets can come later if you want them. At the beginning, simple wins.
Saving with no fun attached
If all your money goals feel grim, it is harder to stick with them. The near-term goal bucket gives your plan some life.
Forgetting to raise transfers after paying off debt
This is a smart time to grow your savings habit. If you just finished a loan or credit card payment, roll that freed-up amount into your buckets. We wrote more about that in The ‘Debt-Flip Savings’ Habit: Turn Every Payoff Into a Permanent High‑Yield Raise. It is one of the easiest ways to build momentum without feeling like you cut your lifestyle overnight.
Who this strategy helps most
This setup is especially useful if you:
- Keep dipping into savings and regretting it
- Have irregular expenses that always seem to hit at the worst time
- Want to save for something fun without neglecting your safety net
- Feel stuck by generic “just save more” advice
It is also great for couples who share goals but hate money confusion. Clear bucket names can stop a lot of “wait, I thought that money was for…” conversations.
At a Glance: Comparison
| Feature/Aspect | Details | Verdict |
|---|---|---|
| One big HYSA balance | Easy to open, but all goals blur together and withdrawals can feel stressful | Good for earning interest, weak for peace of mind |
| Three labeled buckets | Separates emergency savings, near-term goals, and irregular expenses inside one system | Best mix of simplicity and clarity |
| Payday automation | Transfers happen before money gets absorbed into normal spending | Strong habit builder and the easiest way to stay consistent |
Conclusion
You do not need a perfect budget to make savings feel useful again. You just need a better container for real life. That is what a high yield savings bucket strategy gives you. One account, three clear goals, and a simple transfer plan tied to payday. It turns savings from a nervous pile of money into a tool you can actually use. And that means you can build an emergency cushion, save for something you care about, and handle life’s random expenses without leaning on credit cards or cutting every small pleasure that makes life feel normal. Start tonight. Name the buckets. Set the transfer. Let the system do the heavy lifting.