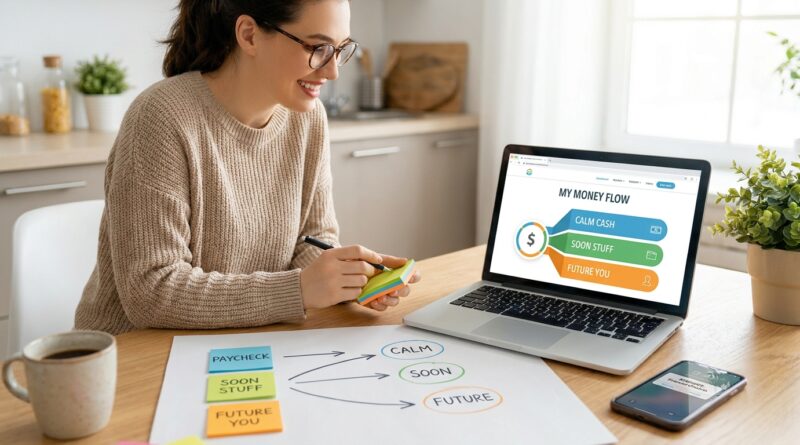
The ‘3-Bucket HYSA Map’ Habit: Give Every Dollar A Job So Your Savings Finally Stick
You did the smart thing. You opened a high-yield savings account. Then real life happened. A car repair popped up, a trip got booked, a yearly bill came due, and suddenly that nice savings balance started sliding right back into checking. That is frustrating, and it happens for a simple reason. If all your money sits in one big blob, every dollar starts to look available. Emergency money, vacation money, and next month’s insurance bill all get mixed together. That makes it far too easy to “borrow” from savings and never quite replace it. The fix is not complicated. You do not need a spreadsheet obsession or a finance app you will quit in two weeks. You just need a simple map. Give your HYSA three clear buckets with names that match real life, and your savings gets a job, a boundary, and a much better chance of actually sticking.
⚡ In a Hurry? Key Takeaways
- To answer how to organize money in a high yield savings account, split it into three buckets: emergency, planned spending, and long-term savings.
- Name each bucket clearly so you know what money is off-limits and what money is safe to use.
- This simple setup helps protect your safety net, lowers random spending from savings, and makes high HYSA rates actually useful.
Why one big savings pile usually fails
Most people are not bad at saving. They are bad at sorting.
That sounds harsh, but it is actually good news. It means the problem is fixable.
When your HYSA has one balance and one label, your brain fills in the blanks. A balance of $8,000 can feel comforting, but what does it really mean? Is $3,000 of that for emergencies? Is $1,200 for property taxes? Is $2,000 for a summer trip? If you do not know, you are far more likely to dip into it.
That is why people keep asking how to organize money in a high yield savings account. The account itself is not enough. The structure is what changes behavior.
The 3-bucket HYSA map
Think of your savings account like a small house with three rooms. Same address. Different purposes.
Bucket 1: Emergency
This is your “leave it alone unless life punches you in the face” money.
Use it for job loss, urgent car repairs, surprise medical bills, emergency travel, or a broken appliance you truly need. Do not use it for concert tickets, holiday shopping, or a weekend getaway you forgot to budget for.
Name it something plain and clear, like:
- Emergency Fund
- Do Not Touch
- True Emergency Only
If you want extra help making this money feel off-limits, the idea in The ‘Emergency Pocket’ HYSA Habit: One Tiny Split That Makes Your Safety Net Feel Spend-Proof is worth a look. The whole point is to stop your safety net from getting mixed in with everyday life.
Bucket 2: Planned Spending
This is money you fully expect to use. That is the whole point.
Think of this bucket as your “coming soon” money. It covers expenses that are not monthly, but are definitely headed your way.
Examples include:
- Insurance premiums
- Holiday gifts
- Travel
- Back-to-school costs
- Home maintenance
- Vet bills for routine care
- Annual subscriptions
This bucket is where many people trip up. They think using savings means they failed. Not true. If you saved ahead for a known expense and then spent it, that is a win.
Bucket 3: Long-Term Savings
This is money for goals that matter, but are not urgent next month.
Maybe that is a house down payment, a bigger emergency cushion, a baby fund, a future move, or a next-car fund. It should be money with a purpose, but not money you need to touch this quarter.
Name it after the goal if possible:
- House Down Payment
- Next Car Fund
- Future Move
- Big Goal Savings
The more specific the label, the harder it is to casually raid.
How to set this up without making it a whole project
You do not need to rebuild your financial life in one night.
Step 1: Look at your current HYSA balance
Take the total and ask a simple question. If this money had to be sorted today, how much belongs in each bucket?
Even rough numbers are fine. You are making a map, not filing taxes.
Step 2: Use separate savings buckets, subaccounts, or nicknames
Many banks let you open multiple savings buckets under one login. If yours does, great. If not, use one HYSA and keep a simple note in your phone with the split. But actual separate buckets are better because they reduce mental math.
Step 3: Rename them like a normal person
Do not call them “Savings 1,” “Savings 2,” and “Savings 3.” That is how money turns back into mush.
Use names your tired Tuesday-night brain will understand instantly.
Step 4: Send new money to the right place on purpose
When payday hits, decide ahead of time what each dollar should do.
For example:
- $100 to Emergency
- $150 to Planned Spending
- $200 to Long-Term Savings
That is the habit. Tiny, clear, repeatable.
A simple real-life example
Let’s say Maya has $6,000 in a HYSA.
- $2,500 goes to Emergency Fund
- $1,500 goes to Planned Spending for car insurance, a wedding trip, and holiday shopping
- $2,000 goes to Long-Term Savings for a future move
Now her car needs $700 in repairs.
If she had one giant savings blob, she might panic and feel like her whole plan is wrecked. Or worse, she might pull money from the wrong goal and forget to replace it.
With the 3-bucket map, she knows exactly what to do. If it is a true urgent repair, she can use Emergency. If she had already set aside car upkeep in Planned Spending, even better. Either way, one expense does not blur the whole picture.
Common mistakes to avoid
Making too many buckets too fast
Yes, some people love ten categories. Most people will not keep that up. Start with three. You can always add more later if your bank makes it easy.
Calling everything an emergency
If the expense is predictable, it is not an emergency. Holidays are not emergencies. Oil changes are not emergencies. Annual fees are not emergencies. They belong in Planned Spending.
Leaving the long-term bucket too vague
“Future” is better than nothing, but “Down Payment” is better than “Future.” Clear names create clear behavior.
Not checking the map once a month
This does not need daily attention. But once a month, take two minutes and ask:
- Is Emergency still intact?
- Is Planned Spending ready for upcoming bills?
- Is Long-Term Savings still moving?
Why this works better than willpower
Because willpower is unreliable.
Labels and structure do some of the work for you. They reduce decision fatigue. They lower the odds that you will treat all savings as spendable just because the number is there.
This is really the heart of how to organize money in a high yield savings account. You are not just chasing a better interest rate. You are building separation between money you can spend soon, money you should not touch, and money meant for future goals.
That separation matters more than people think.
At a Glance: Comparison
| Feature/Aspect | Details | Verdict |
|---|---|---|
| One big HYSA balance | Easy to open, but emergency money, upcoming bills, and goals get mixed together. | Simple at first, risky in real life. |
| 3-bucket naming system | Splits savings into Emergency, Planned Spending, and Long-Term Savings. | Best mix of clarity and ease. |
| Too many savings categories | Can work for detail lovers, but often becomes a chore and gets ignored. | Useful only if you will actually maintain it. |
Conclusion
Right now, a lot of people are finally moving cash off the sidelines into HYSAs, which is smart. But if emergency money, upcoming bills, and long-term savings all sit in one pile, the system gets shaky fast. One rough month, one car repair, or one expensive trip can drain money that was supposed to stay put. The good news is that the fix is small. A simple 3-bucket naming habit keeps your emergency buffer safer, keeps short-term goals funded on time, and still lets you enjoy your money without guilt. It turns a vague savings balance into a clear plan. And that is how today’s high rates start building real, durable wealth instead of just giving you a slightly higher balance you end up spending anyway.